Champions League - Format Dynamics
The Champions League restarts tomorrow with its league stage, now in its third year since it changed from the old group stage. This was a format change with very wide reaching implications and we now have two seasons of data to inform our betting methodologies. I was planning on making a post along these lines anyway but on the @SportsPicks Bet w/ Barnes stream on Saturday, I asked @RobertBarnes about his approach to the league phase, especially with regard to its increased volatility. Since I posted my questions in advance, I wasn't around to clarify what I meant by increased volatility. That's what I'd like to cover in this post.
Under the old group stage format, you had eight groups of four, each team plays each other home and away, then the top two teams progress to the next round. The league stage that replaced it has 36 teams, each playing 8 games, the top 8 teams progress to the round of 16 while the next 16 teams play each other in a playoff round to progress to the last 16. The remaining 10 teams are out and don't go down to the Europa League, which happened with third placed teams in the old group stages. The same number of teams stay live in European football (24) but now you have all of them staying in the Champions League but with less teams going through to the last 16 automatically. There are already two more games in the league phase compared to the old group stage, the playoff round represents and extra two games. So teams' incentives adjust in response.
First incentive change is that since it is harder to get knocked out, each game does not hold the same degree of importance as it used to. You have eight shots to get it right rather than six and you do not face the same opponents home and away, so you play an opponent and that's them done until the knockout stage at least. You don't have to worry that losing to a team means you might finish behind them and consequently third. So teams that would previously have been at risk of going out in the group stage now don't have to do as much to remain live.
The second incentive change is that it is harder to get the highest advantage possible from the league stage. In the old group stage you could win your group with a game or two to spare and you could rotate for the rest of the group. You could also qualify with a game or two to spare and so who wins the group is a nice to have for seeding but it doesn't lead to any difference in games played. In the league phase, you need to finish in the top 8 to avoid the playoff round, so unless you've been winning all your games and you top the league early, there's always something to play for in each round. With the above, this means tactical games, playing for a draw does not have the same gravity as it did in the old group stage.
The third incentive change is that you are no longer competing against three teams, you are competing against the entire field. Winning each game is still the most important objective but goal difference has the ability to put you ahead of teams you don't even play. Tying directly in with the above two paragraphs, this means that game state management, defending narrow leads and tactical draws do not have the same utility for teams in the league format, so you have an incentive to run up the score that didn't exist previously. In the final league stage game, this means teams have very real trade-offs to make with limited information which directly impacts volatility pricing for these games.
Based on the data from the last two seasons, draw rates are down. They used to average about one in five games in the old group stage format, so around twenty percent, now the draw rate is in the teens. It was low teens first season and mid teens second season. We have also seen an increase in goals scored. Old format goals per game was a little over 3 goals per game, new format it's over 3.25 goals per game, closer to three and a third. This might not seem massive but it has big implications for main game lines. Every team will react to the league format differently but we have seen enough to observe a net drift towards higher totals and lower draws. There is also potential for more asymmetric goal distributions, something betting markets find more difficult to model due to the non linearities it introduces, so this impacts both moneyline and spread pricing more generally. I am not sure on the precise impact on both teams to score markets but I suspect it pushes that up too. Since the seeding means you meet two teams from each of the four seeding pots, this means that the "strength of schedule", to borrow some NFL terminology, is more consistent than in the old format.
The league stage format is one which can't be approached like the old group stage format, neither can it be approached like a domestic league, and it definitely cannot treat the last set of matches, all eighteen of which are played at the same time, as if they were equivalent to the earlier matches. I would be cautious about draws because I think fair draw pricing will be more sensitive to the manager's tactical tendencies. There may be value on certain big market teams to cover big spreads due to the goal difference factor. I am not sure if game totals and BTTS markets are accurately pricing the league phase dynamics so I am going to watch out for those. There will also be a lot of "on a first pass" matchups of teams that haven't played each other before in their current incarnations so there will more spots where the game that you see played is not representative of what you would have seen had they played each other twice last year. Certain tactical profiles may adapt to this better than others. We shall see how it unfolds.
In this edition of "Master Class", we're gonna look at Prediction Markets vs Sportsbooks, and why the Prediction Markets are the Future of Sports Betting!! Come join us, as we try to provide you with all the tools to STACK YOUR NICKELS TO THE CEILING!! Feel Free to drop any questions you have in the comments!! Hope This Helps My Friends!! Good Luck, Good Gamblin, & Have The Day You Deserve!!
-Crickett
Two conflicting trends dictate the Senate outcome in 2026. The map heavily favors Republicans, as the competitive Senate seats up lean heavily Republican. By contrast, the election context heavily favors Democrats, with war, recession, realignment and scandal tipping in their direction. A deeper dive reveals why prediction markets still likely undersell Democratic prospects.
First, the idea that Senate midterms favor the party out of power in the White House is belied by both recent and a century of history of Senate elections. Unlike the House, only a third of Senate seats face election in any midterm, and that map dictates outcomes unless the election context is particularly bad for the incumbent party.
Consider that the highly unpopular Biden didn’t lost any net Senate seats in 2022 and Trump added Senate seats in the Democratic friendly cycle in 2018. Equally, Clinton didn’t lose net Senate seats in 1998 nor did W. in 2002. Even low-approval election cycles like 1966 and 1982 didn’t produce a big swing in the Senate. Indeed, since 1934, the party in power only lost 10% or more of their Senate seats (4+) less than half of the time. Democrats need a flip of exactly that — at least 4 Senate seats — to retake power in the Senate.
Then take a look at the map, and you can see the reason for optimism in GOP circles and some traders in the prediction markets. Only 2 GOP-held seats are in states Trump won by less than double digits, while 2 Democratic-held seats are in states Trump won, and one of those GOP held seats features a long-time incumbent who typically runs double-digits ahead of the GOP norm (Collins in Maine). This is why the GOP entered the year believing odds of losing the Senate were remote, and the prediction markets mostly concurred.
But this ignores the counter-trend: the degree of election dismay with the incumbent party in the White House, and the reasons for that dismay. Presidential job approval has not been a neat proxy for Senate midterms because it depends on the reason for that dissatisfaction in the electorate. Four factors drive Senatorial midterms: war, recession/cost of living, realignment, and scandal. When two of those four factors are not present and don’t dominate, then the incumbent party’s odds of losing 4+ Senate seats drops to less than 20%. By contrast, when two of those four factors are present and do predominate, then the odds of the incumbent party losing 4+ Senate seats rises to 100%. Indeed, the median number of Senate seats lost when some combination of war, recession, realignment and scandal, are present, the White House party loses at least 8 Senate seats.
A few examples: while FDR added Senate seats in 1934 midterms, he lost 9 in 1938 midterms due to the combination of recession and scandal (trying to stack SCOTUS). 1942 and 1946 gave us war and recession to cost Democrats 8 and 12 Senate seats alike. 1950 gave us war again and scandals concerning the war costing Democrats 5 Senate seats. 1958 gave us recession and scandal, costing Ike 15 Senate seats. While JFK added Senate seats in 1962 and Nixon added Senate seats in 1970, only Watergate and stagflation in 1974 or the combination of Iran Contra and vulnerable class of 1980 incumbents cost the incumbent party 4 or more Senate seats until the realignment election of 1994, where evangelicals shifted their down-ballot voting to the GOP en masse. It took war and scandal in 2006 to see the Senate switch 4+ Senate seats again.
That’s the story of 2026: a very GOP favorable Senate map versus a very Democratic friendly election cycle. The GOP enters election season with all four factor present: war, recession/cost of living, realignment, and scandal. The Iran War was already deeply unpopular, and it’s impact on the economy in gas and diesel prices turns Americans sour on their current economic prospects, as wages fall behind, housing and health care feel increasingly unaffordable, labor force participation continues to drop, the the mirage of AI keeps the GDP just above a technical recession. The Epstein scandal remains one of the worst scandals in American political history, and Trump managed to associate himself deeply with the scandal in his handling of it. Then the realignment, as the new Trump 2024 voters joined the Obama-Trump converts of 2016 in abandoning GOP identity, already evident in surveys and primary participation.
A quintet of voter groups appear to be realigning away from the Republican brand — hispanic voters, black voters, industrial area voters, libertarian-leaning voters, and war-skeptical voters alike. This realigning electorate shows up disproportionately in key Senate contests. The war-skeptical voters in states like Maine, New Hampshire, Ohio, Michigan, Iowa, Montana, Nebraska, and Alaska (these are the states W failed to gain in between 2000 and 2004 due to the Iraq War before it even turned unpopular). The hispanic voters in states like Florida and Texas. The African-American voters in states like North Carolina and Georgia. The industrial voters in Ohio and Michigan. The libertarian leaving voters in states like New Hampshire, Alaska, Texas and Florida.
Thus, many of the states that seem “Safe” on the map are anything but, as their realigning electorates shift back against the Republican brand, with all of them having recent histories in electoral cycles of favoring Democrats or being true swing states. Take states like Florida and Texas where suburban margins began to erode for the GOP in the Trump era but countered that by massive margin shifts in hispanic and black precincts. Primary participation, voter identification, and public opinion surveys show those black and hispanic voters shifting back massively away from the GOP brand, which, given the erosion in some suburban areas and losses with younger generations, makes states Florida and Texas closer to competitive than double-digit leans.
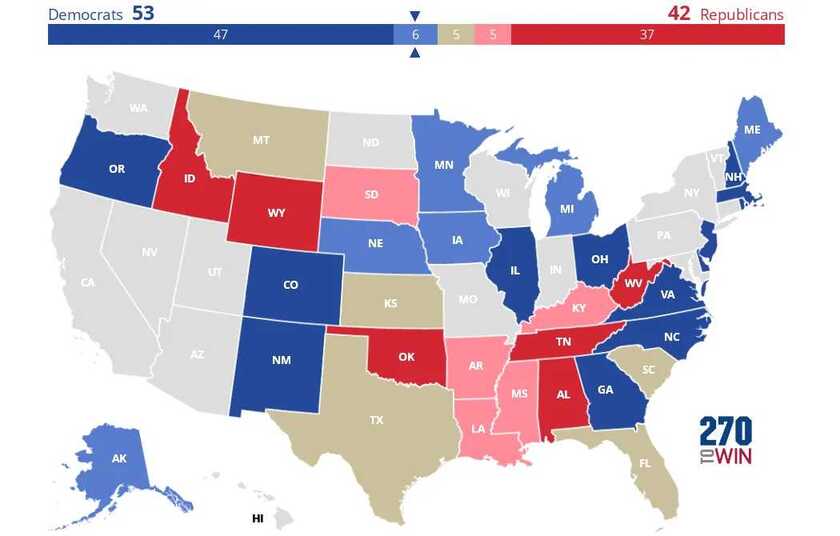
In big swing election cycles, even “safe” Senate seats can suddenly turn razor close, as Bob Dole found out in 1974, barely holding on to his Kansas seat before being the VP nominee two years later. Strong independent candidates in Kansas, Nebraska, South Dakota and Montana may pose a unique threat to GOP held seats, as the Nebraska race in 2024 showed, with Osborn running 17 points ahead of Harris’ margin in the state. Democrats field the much better candidate in Ohio with a proven track record of out-performing Democratic margins in the state, while the Texas GOP nominee faces abandonment from his own party after they spent over $100M bashing him in the state for a disliked party incumbent. Alaska primary results suggest the Democratic nominee already holds the edge in that ranked choice voting state, while the famed cross-over support for Collins in Maine appears to be fading with newer generations taking over the voter rolls. My current map would be as follows, with surprising closer-than-expected races in Montana, Kansas, Louisiana, Florida, Mississippi, South Dakota, South Carolina and Kentucky, and a median map of Democrats holding 53+ Senate seats after the 2026 elections.

If past is prologue, the map won’t save the GOP in 2026, and an ever bigger tsunami may be incoming than anyone in Washington expects.